
FREE NEWSLETTER

Wall Street feeds the fantasy that we can beat the market, because the fantasy is a great moneymaker—for Wall Street.

Latest PostsAll Discussions »

Taxes

Sourcing Taxes for Roth Conversions

"Thanks, Mark. You’re right. Not much i can do about the $12K OBBB senior deduction. I think that’s probably lost but i do plan to be strategic tip toe’ing around IRMAA brackets."
- Mark Ukleja
Read more »

Health

Medicare Part D premium shock 2027

"Shopping plans won’t do much good; the cause of most increases is not because of underlying costs, but because laws and political decisions have simply shifted costs and the insured population will pick up the different. For some reason the thinking is, don’t send money to insurance companies because they are ripping us off. Instead let the patients send it and government saves money. This is an amazing smoke and mirrors strategy to find another scapegoat. I doubt most Medicare beneficiaries will understand what is actually going on. 😢🥵 Most people won’t believe this, but insurance companies are not the enemy, they don’t make excessive profits, their net profit margins are low, about the same as regulated utilities. But I guess we have to have someone else to blame. The ironic thing is the majority of workers with employer coverage don’t even have insurance. Their employer is self-insured and the company on their ID “insurance” card just processes claims for a fee and has no risk for claim payments."
- R Quinn
Read more »

Retirement

Will Congress Wait Until the Last Minute on Social Security?

"Members of Congress are like children. Procrastinate until the very last minute to do anything. How many government shutdowns threats have we endured because they are mostly all child-like. Just please remember you are working for your constituents, not yourselves."
- Ted Tompkins
Read more »

Behavior

Time Is Priceless

"Andrew-You are a fantastic writer-keep it up!"
- Philip Russell
Read more »

From HumbleDollar Founder Jonathan Clements
Lists

Why HumbleDollar?

IN OUR 20s, WE TEND to be a confident lot: We figure we know what we want from our life, that the goal is…
Read more »

Behavior

My favorite question.

"You are indeed rich. Rich is not just about money."
- Steve Skillman
Read more »

Investing

Financial Lessons

WHAT'S THE MOST important idea in personal finance? It’s hard to single out just one, but over the years, I’ve found the following dozen ideas to be among the most useful.
  1. Whether it’s on TV or online, there’s never any shortage of market prognosticators. Especially during a bull market, everyone seems to have an opinion on where things are headed. The reality, though, is that people can only guess about how the economy, the market or any individual investment will perform. Convincing as they might sound, no one has a crystal ball. That’s why, when it comes to investing, I suggest taking an evidence-based approach, one that relies as much as possible on data and research rather than on the simple stories, anecdotes and sayings that are so prevalent among market commentators.
  2. What does the data tell us? Among the most significant research in recent years is the work of Hendrik Bessembinder. In looking at the historical returns of stocks, he found that just a tiny fraction—only 4%—have accounted for the vast majority of the market’s gains over and above what Treasury bills paid, and the median stock actually delivered a negative return. This is one of the key reasons I recommend index funds rather than picking individual stocks or investing in an actively-managed fund. Identifying that 4% is almost impossibly difficult. But if you invest in a broad-based index fund, you’ll have a high likelihood of owning the next Apple or Nvidia.
  3. Be careful not to miss the forest for the trees. The most important driver of investment risk and return for most people, most of the time, is asset allocation. In other words, the dollars you have in stocks vs. in bonds or in cash will almost always be the most consequential decision. It’s easy to lose sight of that, though, because so much of the investment commentary from day to day focuses on details like small differences in fund expenses or small differences in bond yields. To be sure, details can be important, but only after considering the big picture.
  4. Another challenge in investing is that certain rules of thumb gain so much popularity that they end up being seen as rules rather than just guidelines. For example, some say that the percentage of a portfolio allocated to bonds should be equal to an investor’s age. To me, that’s illogical. Consider Bill Gates. He’s 70 years old, but it stands to reason that he shouldn’t have the same asset allocation as any other 70-year-old. Rules of thumb are useful as points of reference, but we shouldn’t lose sight of the fact that everyone’s situation is different, and our investments should reflect that. More to the point, don’t worry if you’re doing something different from the next person.
  5. Buy insurance, but only to protect against losses you couldn’t absorb on your own. What does this mean in practice? In many cases, it’s possible to significantly cut insurance premiums by increasing deductibles. For example, if you have a seven-figure net worth, you might consider raising the deductible on your homeowner’s insurance to $5,000 or $10,000 or even more. Similarly, you might re-evaluate your life insurance as your net worth grows. You’ll likely become “self-insured” at some point, and then you could reduce or drop that coverage.
  6. Personal finance is quantitative, but we should never make decisions based only on the numbers. For example, a common question is how much cash to keep on hand. While we could work out an optimal number on a calculator, that shouldn’t be the final answer. You should also consider what would provide you with peace of mind. That is equally important.
  7. Be wary of the psychological pitfall known as recency bias. This is the tendency to extrapolate from recent experience and to downplay the possibility that things might change. The most famous example? In the late-1920s, when the stock market was booming, Yale University economist Irving Fisher declared that the stock market had reached a “permanently high plateau.” Just nine days later, the market crashed, ultimately dropping 89% from its peak.
  8. Avoid high fees. The research firm Morningstar once wrote, “If there’s anything in the whole world of mutual funds that you can take to the bank, it’s that expense ratios help you make better decisions. In every single time period and data point tested, low-cost funds beat high-cost funds.”
  9. Keep things simple. Most importantly, I would be wary of investments that aren’t easily understood. Not only can this help keep investment costs down, but it also makes it much easier to monitor your financial picture. Legendary fund manager Peter Lynch said it best: “Never invest in any idea you can't illustrate with a crayon.”
  10. Avoid “interesting” investments. So far this year, Wall Street has introduced more than 1,000 new exchange-traded funds (ETFs). How many of these are worth your attention? My guess is you could probably count them on one hand. More than 80% of these new funds are actively-managed, and more than 30% employ leverage. And there are more to come. Fund companies recently filed paperwork to create ETFs that will track the performance of major league sports teams. They won’t actually own shares in the teams; instead, they’re expected to rise and fall in response to each team’s wins and losses.
  11. For years, I’ve argued that bitcoin isn’t a valid investment. Even though it’s gone way up since I first made that argument, I still feel the same way, and for the same reason: because it lacks intrinsic value. Unlike stocks or bonds, it doesn’t generate any dividends or interest. Bitcoin’s price is not anchored to anything measurable or tangible, and that’s why, in my opinion, its price is so volatile.
  12. When it comes to investment risk, investors’ attention usually turns to the stock market. That makes sense, but as we’ve seen this year, bonds are not without risk. And unfortunately, the total-bond market index, which is often seen as the simplest, set-it-and-forget-it option, is one that carries quite a bit of risk. If you’re choosing bond investments, my recommendation is to pay attention to a metric known as duration. This tells you how sensitive a bond, or bond fund, will be to interest rate changes. In my view, investors should hold a sizable portion of their bond investments in a fund, or in individual bonds, with a duration of less than two years.
Adam M. Grossman is the founder of Mayport, a fixed-fee wealth management firm. Sign up for Adam's Daily Ideas email, follow him on X @AdamMGrossman and check out his earlier articles.
Read more »

In Retirement

Widow’s Penalty Redux

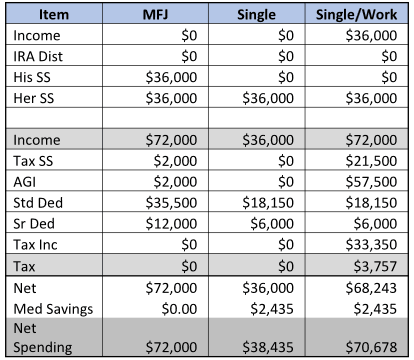
A RECENT post by achnk53 about the impact of a spouse’s death on the survivor’s taxes piqued my interest.  The post referenced an interesting Kiplinger article about the “Widow’s Penalty”, or the negative tax implications on a surviving spouse after the death of a spouse. A surviving spouse can file Married Filing Jointly (MFJ) in the year of their spouse’s death. In the full year following the spouse’s death you must file Single.  There are some beneficial filing rules for surviving spouses who have dependent children, but that is beyond this post. Nine days later John Urban published an article running the tax numbers for 3 different retiree scenarios, and using the data to provide some excellent suggestions for readers.  In between these two articles I had run some similar case studies to understand the impacts. I ran some case studies using the 2026 Dinkytown 1040 Calculator.  I considered a “lower" income retired couple.   The impact of one spouse passing is very dependent on the sources of income. Assume the retired couple were each receiving $36,000 in annual SS benefits. They have no other sources of income.  The couple filing jointly would have no taxable income, and no tax for 2026.  Had the husband died in 2025, the surviving widow would have seen her income reduced to $36,000. If she needed the lost income, and found a job that paid $36,000, her income would match the original $72,000. But $21,500 of her SS benefit would be taxable, her taxable income would be $33,350, and her annual tax bill would be $3,757.  The table below shows the details of this analysis: Tax Calculation After accounting for the reduction in Medicare related spending, she has similar spending power. But she had to go back to work to achieve that.  This, and the previous examples, reinforce the importance of understanding a couple’s financial details before and after the passing of a spouse. Income will likely be reduced, but expenses may also be reduced. Lower income retirees who depend primarily on both partners SS benefits may see the biggest impact. I also ran a comparison of our tax return for 2026, for both MFJ and if my wife filed single.  I assumed our income consisted of my pension, my wife’s SS benefit, and my SS benefit had I claimed it on January 1, 2026. When I die my wife will receive 75% of my pension, and my higher SS benefit.  The results were not surprising.
  • Her total income would be 68% of our combined pre-death income.
  • Her annual tax bill would be $1,250 more than our joint tax bill.
  • Her effective tax rate would increase by 4.2%.
  • 85% of her SS benefits would be taxable
  • Her spendable income after taxes would be about 65% of the joint amount.
  • She would lose about 20% of the new Senior Deduction
  • She would have no NJ State Tax liability
I then ran an additional scenario with the same assumptions, but also assuming we were 4 years older and would both have to take initial RMDs in 2026.  This scenario reflects one of the concerns frequently expressed when discussing this topic – what happens when the surviving spouse is responsible for reporting the income from both RMDs on her Single tax return. The results changed to reflect the scenario. 
  • Her total income would be about 79% of our combined pre-death income.
  • Her annual tax would be $708 more than the joint tax filing.
  • Her effective tax rate would increase by 3.8%.
  • Her spendable income after taxes would be about 80% of the joint amount.
  • She would lose all of the new Senior Deduction.
  • Her NJ State Income tax would be $540 more than the joint tax filing.
  • She would be pushed up one IRMAA bracket in 2028.
These results are a simplified look at our finances today.  My pension and my wife’s SS benefit cover our non-discretionary, and a decent portion of our discretionary, expenses. The wild card is travel – how much we spend in any year is our choice and may require additional income. I’m about 11 months from claiming my SS benefit, at which point virtually all of our expenses will be covered in a fairly tax-efficient way.  RMDs are still 4 years away. This was a good exercise to get a feel of how my demise would impact my wife’s finances. It would have some financial impacts, but I believe our plan can handle them. I’m considering running some more detailed projections varying the age at death to assess the impacts, but a quick look made me reasonably confident our retirement savings will be adequate, even considering long term care. I will also continue to look at Roth conversions each year.   Richard Connor is a semi-retired aerospace engineer with a keen interest in finance. He enjoys a wide variety of other interests, including chasing grandkids, space, sports, travel, winemaking and reading. Follow Rick on Twitter @RConnor609 and check out his earlier articles.
Read more »

In Retirement

Is your retirement plan counting on a Social Security COLA in the future?

"Little wonder many young people view SS and Medicare as huge scams that simply transfer their income to older generations. Using regressive taxes to boot. Many SS recipients receive much more than they put in."
- Paul Ward
Read more »

Health

My Name is Dan, and I’m a CPAP User

"I was super-resistent to using the CPAP at night. It took me several tries over several years to get it right. Here are two things that turned it around: 1) I wore the mask during the day for increasing amounts of time so I'd get acclimated to the 'feel' of it. This helped me to mentally accept the device and not resist it at night. 2) I use a Breath Right nasal strip each evening to keep my nostrils open. This removes the feeling of restricted nose breathing (which kept me from falling asleep). Good luck. Hope this helps."
- Doug Burke
Read more »

In Retirement

Keep an eye on Medigap policies

"Premiums are not based on individual usage. They vary by whether they are community based, entry age based or current age based."
- R Quinn
Read more »

In Retirement

The Security Money Can’t Buy

"Mark, Pushing ourselves to build those friendships is so important for men, and you gave a great example. That feeling of an empty house is exactly what I feel when Rachel is away, too."
- Dennis Friedman
Read more »

Taxes

Sourcing Taxes for Roth Conversions

"Thanks, Mark. You’re right. Not much i can do about the $12K OBBB senior deduction. I think that’s probably lost but i do plan to be strategic tip toe’ing around IRMAA brackets."
- Mark Ukleja
Read more »

Health

Medicare Part D premium shock 2027

"Shopping plans won’t do much good; the cause of most increases is not because of underlying costs, but because laws and political decisions have simply shifted costs and the insured population will pick up the different. For some reason the thinking is, don’t send money to insurance companies because they are ripping us off. Instead let the patients send it and government saves money. This is an amazing smoke and mirrors strategy to find another scapegoat. I doubt most Medicare beneficiaries will understand what is actually going on. 😢🥵 Most people won’t believe this, but insurance companies are not the enemy, they don’t make excessive profits, their net profit margins are low, about the same as regulated utilities. But I guess we have to have someone else to blame. The ironic thing is the majority of workers with employer coverage don’t even have insurance. Their employer is self-insured and the company on their ID “insurance” card just processes claims for a fee and has no risk for claim payments."
- R Quinn
Read more »

Retirement

Will Congress Wait Until the Last Minute on Social Security?

"Members of Congress are like children. Procrastinate until the very last minute to do anything. How many government shutdowns threats have we endured because they are mostly all child-like. Just please remember you are working for your constituents, not yourselves."
- Ted Tompkins
Read more »

Behavior

Time Is Priceless

"Andrew-You are a fantastic writer-keep it up!"
- Philip Russell
Read more »

From HumbleDollar Founder Jonathan Clements

Lists

Why HumbleDollar?

IN OUR 20s, WE TEND to be a confident lot: We figure we know what we want from our life, that the goal is…
Read more »

Behavior

My favorite question.

"You are indeed rich. Rich is not just about money."
- Steve Skillman
Read more »

Investing

Financial Lessons

WHAT'S THE MOST important idea in personal finance? It’s hard to single out just one, but over the years, I’ve found the following dozen ideas to be among the most useful.
  1. Whether it’s on TV or online, there’s never any shortage of market prognosticators. Especially during a bull market, everyone seems to have an opinion on where things are headed. The reality, though, is that people can only guess about how the economy, the market or any individual investment will perform. Convincing as they might sound, no one has a crystal ball. That’s why, when it comes to investing, I suggest taking an evidence-based approach, one that relies as much as possible on data and research rather than on the simple stories, anecdotes and sayings that are so prevalent among market commentators.
  2. What does the data tell us? Among the most significant research in recent years is the work of Hendrik Bessembinder. In looking at the historical returns of stocks, he found that just a tiny fraction—only 4%—have accounted for the vast majority of the market’s gains over and above what Treasury bills paid, and the median stock actually delivered a negative return. This is one of the key reasons I recommend index funds rather than picking individual stocks or investing in an actively-managed fund. Identifying that 4% is almost impossibly difficult. But if you invest in a broad-based index fund, you’ll have a high likelihood of owning the next Apple or Nvidia.
  3. Be careful not to miss the forest for the trees. The most important driver of investment risk and return for most people, most of the time, is asset allocation. In other words, the dollars you have in stocks vs. in bonds or in cash will almost always be the most consequential decision. It’s easy to lose sight of that, though, because so much of the investment commentary from day to day focuses on details like small differences in fund expenses or small differences in bond yields. To be sure, details can be important, but only after considering the big picture.
  4. Another challenge in investing is that certain rules of thumb gain so much popularity that they end up being seen as rules rather than just guidelines. For example, some say that the percentage of a portfolio allocated to bonds should be equal to an investor’s age. To me, that’s illogical. Consider Bill Gates. He’s 70 years old, but it stands to reason that he shouldn’t have the same asset allocation as any other 70-year-old. Rules of thumb are useful as points of reference, but we shouldn’t lose sight of the fact that everyone’s situation is different, and our investments should reflect that. More to the point, don’t worry if you’re doing something different from the next person.
  5. Buy insurance, but only to protect against losses you couldn’t absorb on your own. What does this mean in practice? In many cases, it’s possible to significantly cut insurance premiums by increasing deductibles. For example, if you have a seven-figure net worth, you might consider raising the deductible on your homeowner’s insurance to $5,000 or $10,000 or even more. Similarly, you might re-evaluate your life insurance as your net worth grows. You’ll likely become “self-insured” at some point, and then you could reduce or drop that coverage.
  6. Personal finance is quantitative, but we should never make decisions based only on the numbers. For example, a common question is how much cash to keep on hand. While we could work out an optimal number on a calculator, that shouldn’t be the final answer. You should also consider what would provide you with peace of mind. That is equally important.
  7. Be wary of the psychological pitfall known as recency bias. This is the tendency to extrapolate from recent experience and to downplay the possibility that things might change. The most famous example? In the late-1920s, when the stock market was booming, Yale University economist Irving Fisher declared that the stock market had reached a “permanently high plateau.” Just nine days later, the market crashed, ultimately dropping 89% from its peak.
  8. Avoid high fees. The research firm Morningstar once wrote, “If there’s anything in the whole world of mutual funds that you can take to the bank, it’s that expense ratios help you make better decisions. In every single time period and data point tested, low-cost funds beat high-cost funds.”
  9. Keep things simple. Most importantly, I would be wary of investments that aren’t easily understood. Not only can this help keep investment costs down, but it also makes it much easier to monitor your financial picture. Legendary fund manager Peter Lynch said it best: “Never invest in any idea you can't illustrate with a crayon.”
  10. Avoid “interesting” investments. So far this year, Wall Street has introduced more than 1,000 new exchange-traded funds (ETFs). How many of these are worth your attention? My guess is you could probably count them on one hand. More than 80% of these new funds are actively-managed, and more than 30% employ leverage. And there are more to come. Fund companies recently filed paperwork to create ETFs that will track the performance of major league sports teams. They won’t actually own shares in the teams; instead, they’re expected to rise and fall in response to each team’s wins and losses.
  11. For years, I’ve argued that bitcoin isn’t a valid investment. Even though it’s gone way up since I first made that argument, I still feel the same way, and for the same reason: because it lacks intrinsic value. Unlike stocks or bonds, it doesn’t generate any dividends or interest. Bitcoin’s price is not anchored to anything measurable or tangible, and that’s why, in my opinion, its price is so volatile.
  12. When it comes to investment risk, investors’ attention usually turns to the stock market. That makes sense, but as we’ve seen this year, bonds are not without risk. And unfortunately, the total-bond market index, which is often seen as the simplest, set-it-and-forget-it option, is one that carries quite a bit of risk. If you’re choosing bond investments, my recommendation is to pay attention to a metric known as duration. This tells you how sensitive a bond, or bond fund, will be to interest rate changes. In my view, investors should hold a sizable portion of their bond investments in a fund, or in individual bonds, with a duration of less than two years.
Adam M. Grossman is the founder of Mayport, a fixed-fee wealth management firm. Sign up for Adam's Daily Ideas email, follow him on X @AdamMGrossman and check out his earlier articles.
Read more »

In Retirement

Widow’s Penalty Redux

A RECENT post by achnk53 about the impact of a spouse’s death on the survivor’s taxes piqued my interest.  The post referenced an interesting Kiplinger article about the “Widow’s Penalty”, or the negative tax implications on a surviving spouse after the death of a spouse. A surviving spouse can file Married Filing Jointly (MFJ) in the year of their spouse’s death. In the full year following the spouse’s death you must file Single.  There are some beneficial filing rules for surviving spouses who have dependent children, but that is beyond this post. Nine days later John Urban published an article running the tax numbers for 3 different retiree scenarios, and using the data to provide some excellent suggestions for readers.  In between these two articles I had run some similar case studies to understand the impacts. I ran some case studies using the 2026 Dinkytown 1040 Calculator.  I considered a “lower" income retired couple.   The impact of one spouse passing is very dependent on the sources of income. Assume the retired couple were each receiving $36,000 in annual SS benefits. They have no other sources of income.  The couple filing jointly would have no taxable income, and no tax for 2026.  Had the husband died in 2025, the surviving widow would have seen her income reduced to $36,000. If she needed the lost income, and found a job that paid $36,000, her income would match the original $72,000. But $21,500 of her SS benefit would be taxable, her taxable income would be $33,350, and her annual tax bill would be $3,757.  The table below shows the details of this analysis: Tax Calculation After accounting for the reduction in Medicare related spending, she has similar spending power. But she had to go back to work to achieve that.  This, and the previous examples, reinforce the importance of understanding a couple’s financial details before and after the passing of a spouse. Income will likely be reduced, but expenses may also be reduced. Lower income retirees who depend primarily on both partners SS benefits may see the biggest impact. I also ran a comparison of our tax return for 2026, for both MFJ and if my wife filed single.  I assumed our income consisted of my pension, my wife’s SS benefit, and my SS benefit had I claimed it on January 1, 2026. When I die my wife will receive 75% of my pension, and my higher SS benefit.  The results were not surprising.
  • Her total income would be 68% of our combined pre-death income.
  • Her annual tax bill would be $1,250 more than our joint tax bill.
  • Her effective tax rate would increase by 4.2%.
  • 85% of her SS benefits would be taxable
  • Her spendable income after taxes would be about 65% of the joint amount.
  • She would lose about 20% of the new Senior Deduction
  • She would have no NJ State Tax liability
I then ran an additional scenario with the same assumptions, but also assuming we were 4 years older and would both have to take initial RMDs in 2026.  This scenario reflects one of the concerns frequently expressed when discussing this topic – what happens when the surviving spouse is responsible for reporting the income from both RMDs on her Single tax return. The results changed to reflect the scenario. 
  • Her total income would be about 79% of our combined pre-death income.
  • Her annual tax would be $708 more than the joint tax filing.
  • Her effective tax rate would increase by 3.8%.
  • Her spendable income after taxes would be about 80% of the joint amount.
  • She would lose all of the new Senior Deduction.
  • Her NJ State Income tax would be $540 more than the joint tax filing.
  • She would be pushed up one IRMAA bracket in 2028.
These results are a simplified look at our finances today.  My pension and my wife’s SS benefit cover our non-discretionary, and a decent portion of our discretionary, expenses. The wild card is travel – how much we spend in any year is our choice and may require additional income. I’m about 11 months from claiming my SS benefit, at which point virtually all of our expenses will be covered in a fairly tax-efficient way.  RMDs are still 4 years away. This was a good exercise to get a feel of how my demise would impact my wife’s finances. It would have some financial impacts, but I believe our plan can handle them. I’m considering running some more detailed projections varying the age at death to assess the impacts, but a quick look made me reasonably confident our retirement savings will be adequate, even considering long term care. I will also continue to look at Roth conversions each year.   Richard Connor is a semi-retired aerospace engineer with a keen interest in finance. He enjoys a wide variety of other interests, including chasing grandkids, space, sports, travel, winemaking and reading. Follow Rick on Twitter @RConnor609 and check out his earlier articles.
Read more »

In Retirement

Is your retirement plan counting on a Social Security COLA in the future?

"Little wonder many young people view SS and Medicare as huge scams that simply transfer their income to older generations. Using regressive taxes to boot. Many SS recipients receive much more than they put in."
- Paul Ward
Read more »

Free Newsletter

Get Educated

Manifesto

NO. 3: WE SHOULD focus relentlessly on what we want from our financial life. That’ll motivate us to save, drive our investment strategy—and help ensure we pursue the goals we care about most.

Truths

NO. 116: AVOIDING probate is a big cost savings in some states—but not others. A local attorney can tell you how things stand in your state. If probate is costly, you might place assets in a revocable living trust. That can also be a smart move if you own a house in another state—and face the prospect of your estate passing through probate in two states.

think

ILLUSION OF CONTROL. If we shake the dice vigorously, we feel we’re more likely to get the roll we want. Similarly, if we follow the stock market closely and trade often, we feel more control over our returns. But in truth, this can hurt results, as we act impulsively and rack up costs. A better strategy: Focus on things we can control, like risk, taxes and expenses.

act

SEARCH FOR UNCLAIMED property. Every state has a program for returning lost and forgotten assets to their rightful owners. Those assets include stocks, uncashed dividends, bank accounts, traveler’s checks, the contents of safe deposit boxes and utility company security deposits. You can find further details and links to state websites at Unclaimed.org.

Two-minute checkup

Manifesto

NO. 3: WE SHOULD focus relentlessly on what we want from our financial life. That’ll motivate us to save, drive our investment strategy—and help ensure we pursue the goals we care about most.

Spotlight: Life Events

Hitting the Pause Button

New Year’s Eve is the ultimate reminder that the clock never stops. As we prepare to flip the calendar, it’s natural to look back at the year, and the decades, gone by. We often focus on what we want to change in the future, but rarely do we consider which part of the journey we’d actually like to keep.
Youth has many advantages—health, strength, vigor, and vitality. Everything feels possible, and you’re certain you know what’s right and wrong in the world.

Read more »

The Jonathan I Found: Through Others’ Eyes

WHEN MY YOUNGER brother Jonathan died, I thought I knew who he was.
After all, we had shared a childhood in England, years together at boarding school, family adventures in Bangladesh, and more than six decades as brothers. I knew the journalist the world admired, the devoted husband and father, and the man whose words quietly helped millions of readers live richer lives, not simply financially, but personally as well.
I was wrong.
Over the past several months,

Read more »

Questions Matter

My hat’s off to the couples that got hitched right out of school and stayed that way, happily. That was not my reality. Young love, often ignited by intense physical attraction, often doesn’t ask the hard questions, or require clear answers even if the right questions are asked. And while achieving the age of 73 doesn’t make me an expert, I think everyone is entitled to my opinion, so here goes😉.
That intense physical energy is going to change over time,

Read more »

Financial Fraud

RECENTLY, A FELLOW—let’s call him Tom—contacted me with a distressing story of financial fraud. I’ll describe what happened then review steps you might take to prevent this same sort of thing.
Tom first noticed there might be a problem when he spotted a larger-than-average withdrawal from his checking account. The payee was a 529 college savings plan. But because Tom and his wife—let’s call her Jane—have 529 accounts for their children, the transaction almost went unnoticed.

Read more »

Widow’s IRA Choice

WHEN A HUSBAND dies, his widow inherits his IRA. Somewhere in the paperwork of the months that follow there is a decision to make, and nobody presents it to her as one. She can take the account as her own, or she can leave it titled as inherited.
Taking it as her own means filling something in. Leaving it means doing nothing, and the IRS tells custodians they may assume that is what she wants.

Read more »

What’s Really On My Mind

MY RETIREMENT HAS been wonderful so far. Honestly, sometimes I have to stop and remind myself how lucky I am. Rachel and I have our health and enjoy each other’s company, which is not always true when a couple retires. However, there are four things that concern me as I reach my mid-70s.
Loneliness
I tried calling Mark, my old high school friend, a couple of weeks ago, and I haven’t heard from him.

Read more »

Spotlight: Wilhelm

The 4 Year Rule for Retirement Spending

Ben Carlson's column today is a reprint of a method for sustainable retirement spending. You start by calculating your spending requirements in retirement (although I don't see an allowance for inflation) and have four year's worth set aside in cash or cash equivalents by the time you retire. Then there are rules for when you withdraw from cash or stock, and when you replenish cash. It sounds like the remainder of the portfolio is all in stock. I didn't follow that method, as I only have 50% of my portfolio in stock, but it is an interesting approach, and worked for him, despite starting retirement in early 2000.
Read more »

Gift to Myself

LATE LAST OCTOBER, I was one of the first to move into the new building at my chosen continuing care retirement community, or CCRC. Now, more than five months later, I’m more confident than ever that I made a good decision. I’m in my mid-70s, single and childless, with relatives 3,000 miles distant in both directions. Both bathrooms at my old home were up 15 stairs. Aging in place was not a good option. Now, I have a large apartment, with two bedrooms, two bathrooms, a den and a balcony. There's plenty of daylight, including in the kitchen, which has full-size appliances and a huge island. The washer and dryer, also huge, have their own closet. My study—with its six bookcases and a big desk—occupies the second bedroom. The setup of both the study and the main bedroom are effectively unchanged from my house. The apartment is cleaned weekly—I'm planning to switch to every other week—and the guy who answers my maintenance requests is great. There’s no shortage of advice on “aging well,” which generally includes recommendations to exercise, eat a healthy diet and stay socially engaged. Since I moved in, I've been using the weight machines and the treadmill in the well-equipped gym, and I'm starting tai chi. In the week ahead, for those of us in independent living, there's a choice of more than 40 exercise classes, including aqua exercise, barre and cardio strength—and that doesn’t count table tennis and pickleball games. Right now, I'm staying with my primary care physician, rather than switching to the onsite clinic, but I’m getting my vaccinations there. I could attend a webinar on tinnitus next week or one on diet later in the month. And I've already seen the continuing care concept at work: A couple of residents injured themselves during…
Read more »

A Nuanced View of FIRE

Well, mostly FI, but some RE. (FIRE standing for Financial Independence, Retire Early). Christine Benz from Morningstar recently attended a CampFI event in Spain, and wrote about her experience here. She comments that "A lot of people have a caricatured perception of the FI community. They assume that everyone is trying to live on $10 a day in order to hang it up at age 35." While she met some young people, she met older people as well. She concludes that she learned some valuable lessons from her fellow attendees. A recommended read.
Read more »

The Medicare Maze

I GREW UP IN ENGLAND, with health-care coverage provided by the National Health Service, so I’m extremely sympathetic to people calling for “Medicare for All.” Still, I do wonder whether they realize that Medicare is neither cheap nor simple. My medical costs in 2021 were more than $10,000, with half of that for a single drug. And it would have been even more without the $3,000 a year kicked in by my former employer. Since I turned age 65, I’ve experienced three varieties of Medicare coverage, and I need to make another coverage decision soon. I thought HumbleDollar's readers might have opinions about my choices—although it’s a gamble either way. To begin, here’s a brief outline of the parts and plans that comprise Medicare. Medicare Part A is hospital coverage. It covers in-patient room, board and nursing care in a hospital, nursing home, skilled nursing facility, hospice and sometimes at home. One could argue that Part A is free since, if you’re eligible for Social Security, you don't pay premiums for Part A. This is the only time where having a spouse affects your coverage: You can qualify based on your spouse's earnings. But Part A really isn’t free. There’s a $1,600 deductible this year for each “hospital benefit period,” plus there are copays after 60 days in the hospital and after 20 days in a skilled nursing facility. Medicare Part B covers outpatient services, such as doctor visits, preventive care, mental health care and certain prescription drugs. Most recipients pay a monthly premium of $164.90 for Part B in 2023. If your modified adjusted gross income, as of two years ago, was above $97,000 for a single filer or $194,000 for joint filers, you’ll pay more. These premium surcharges are known as IRMAA, short for income-related monthly adjustment amount,…
Read more »

Customizing the Safe Withdrawal Rate

The advice I keep seeing says that you can safely withdraw 4% a year (adjusted for inflation) from a 60-40 portfolio over 30 years. This is all well and good, if your portfolio is 60-40 and you start withdrawing at age 70 - or 65 if you are more pessimistic about your longevity. I have always planned based on living to 100, without really hoping to make it that long, so this advice would have worked if I had started drawing on my portfolio at 70. However, I am now 78, and only started withdrawals two years ago. So far I have withdrawn less than 1% a year and the portfolio has increased by more than that. However, my withdrawals will increase as my CCRC fees increase, plus I am planning to travel this year. I was going to write a post asking whether I could increase the percentage, because the portfolio only needed to last 22 years, or should reduce it because my withdrawals would increase more in line with the increase in health care costs than general inflation and because the portfolio is 50-50. Now Morningstar has weighed in with a handy chart covering multiple portfolio allocations and multiple years. It tells me that a 50-50 portfolio should sustain a 5.3% withdrawal rate over 20 years - a significant increase. However, I don't feel inclined to go that high, given the likely trend in health care costs and my CCRC fees. But maybe I should feel more comfortable with 4%? Thoughts?
Read more »

My Magic Wand

ONE REASON I WAITED so long to sell my house was my extreme reluctance to move all my belongings. I didn't want to deal with the hassles involved—because I’d gone through that less than a decade earlier. In 2013, I had the house renovated. I replaced almost all the flooring, with hardwood downstairs, carpet upstairs and tile in the bathrooms. I also updated the kitchen cabinets. That meant, of course, that every single thing in the house had to be moved. I got rid of a few boxes of books. But otherwise, I still had the same amount of stuff in 2022 that I had in 2013. Meanwhile, in 2019, I put down a deposit on a one-bedroom apartment at a local continuing care retirement community, or CCRC. In 2020, I was able to switch to a two-bedroom apartment in a new building, with completion scheduled for some time in 2023. I was finally going to have to move—and to downsize. Fortunately, there wouldn’t be too much downsizing involved. I would move from a 1,520-square-foot, three-bedroom, two-and-a-half bath house to a 1,660-square-foot, two-bedroom, two-bath apartment with den at the CCRC. I could keep my main bedroom, study and living room unchanged. The upshot: All I’d need to do is donate the furniture in my home’s spare bedroom, the dining table and chairs, and the dinette set in the kitchen. For the apartment, I’d buy a new dining set and put it in the den. With an eye to simplifying the move to the CCRC, I decided to sell my house in 2022 and move temporarily to an apartment, while I waited for the CCRC apartment to be ready. There was a fairly new complex near my house, with elevators and a parking garage, where I could rent a two-bedroom, two-bath…
Read more »